Those are:
Today, we're talking about gamma, which is often described as the "delta of delta." We know that delta measures an option's sensitivity to price changes in the underlying - a $1.00 move in the underlying results in a $0.30 move in a chance with a delta of 0.30. Simple enough.
What is Options Gamma?
Gamma works similarly. Gamma measures the delta's sensitivity to a price change in the underlying. An option with a delta of 0.30 and gamma of 0.03 would have a delta of 0.33 following a $1.00 move in the underlying.
The Importance of Gamma
Without proper context, gamma might seem like an exciting metric like those hyper-specific statistics announcers love citing when you're watching football. This quarterback throws interceptions twice as often when targeting defensive backs whose last name starts with a 'B.' Interesting, but does that mean anything?
The gamma of an options position has substantial implications for how the P & L will play out over the life of the position. Positions with positive gamma have very different characteristics than those with negative traits.
To provide a bit of context, Goldman Sachs said this about gamma:
Gamma – the potential delta-hedging of options positions – is one of the more prominent sources of non-fundamental economic activity in global markets. Market makers who delta-hedge their option positions are economically driven to trade substantial amounts of underlying shares or futures strictly as a result of the price of the underlying itself changing, not as a result of fundamental news and without regard to the liquidity available. As a result, gamma can cause markets to overreact to essential news ("short gamma") or under-react to crucial information ("long gamma").
Sometimes gamma can play a huge role in an options position, and other times it's a relative non-factor. Understanding gamma and how it interplays with the other Greeks is vital to knowing when your P&L is driven by gamma.
Just like delta, you can have a positive or negative gamma position. A favorable gamma position is often referred to as "long gamma," as negative gamma is "short gamma."
What is a Long Gamma Options Position?
A trader is a long gamma when his options position has positive gamma. This involves being net-long options.
Most non-professional options traders live in the positive gamma arena. Positions like outright long calls or puts and vertical debit spreads are typical examples of long gamma trades.
As a rule of thumb, long gamma positions are frequently short theta, meaning they suffer from the negative carry of theta decay.
As a result, long gamma positions benefit significantly from strong trending markets, whereas you'll see a slow withering of your P&L in a sideways, range-bound market due to theta decay.
Unlike short gamma positions, your total exposure in a long gamma position increases when you're right on the trade. If you're long a call (a favorable gamma position), your deltas will increase as you're correct on the trade.
This component of long gamma positions makes them far easier to manage than short gamma positions. It's psychologically easy to work positions when your exposure only grows if you're making money already. So long as you size your positions correctly, you don't have to worry about positions getting out of control. And when you're right, you get paid big time.
To enhance the gains, traders might also consider gamma scalping.
What is a Short Gamma Options Position?
Suppose you've been around online options trading discussions like Twitter and Reddit in the last few years. In that case, you're probably already familiar with short gamma positioning, which is responsible for the almighty 'gamma squeeze.'
A short gamma is a net-short option that carries all of the benefits and drawbacks of selling options. A short gamma position is any option position with negative gamma exposure.
A position with negative gamma (short gamma) indicates the position’s delta will decrease when the stock price rises, and increase when the stock price falls. Short call and short put positions have negative gamma
Namely:
- Benefits from low volatility and sideways price action
- Exposure grows in the wrong direction (your position gets more prominent when you're wrong)
- Generally concave payoff profiles (limited gain for potentially more considerable loss)
- Vulnerable to "gamma squeezes."
- Benefits from theta decay
What is a Gamma Squeeze?
A gamma squeeze is an entirely separate subject from identifying the pros and cons of the gamma level in your options positions, but explaining it can illustrate the power of gamma.
A gamma squeeze occurs when too many traders, mostly market makers, get caught in a short gamma position when volatility suddenly comes into a market. Market makers are forced to quickly adjust their delta hedges which further fuels the rally, creating a feedback loop.
Essentially, options traders deduced two things about option market makers:
- They’re frequently short gamma
- They systematically delta hedge
The logical follow-up here is that if a rapid price move occurs while market makers are very short gamma, their hedging response will create a feedback loop, continually pushing the price in the trend's direction.
Here’s how that theoretically works.
-
Market makers are generally short gamma and short options because customers tend to be long options for hedging and speculation purposes.
-
This gets exaggerated in stocks loved by retail traders who love OTM calls, which have high gamma, forcing market makers to get very short gamma.
-
So you already have a hot pot, and a catalyst comes into the market, creating a frenzy of call buying.
- The quick price moves in the underlying forces market makers to adjust their delta hedges, which fuels the rally even further, creating a feedback loop.
How expiration impacts Gamma
Gamma is higher for options that are at-the-money and closer to expiration. A front-month, option will have more Gamma than a LEAPS option with the same strike because the Delta of the near term options move toward either 0 or 1.00 is imminent. With higher Gamma, investors can see more dramatic shifts in Delta as the underlying moves, especially with the underlying around the strike at expiration.
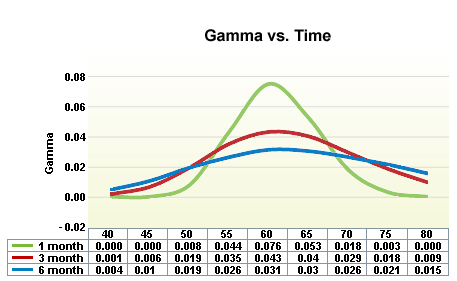
Gamma is lower in the longer-dated LEAPS as more strikes remain possibilities for being in-the-money at expiration because of the amount of time remaining. An at-the-money-option Delta is typically the most sensitive to moves in the underlying (hence higher Gamma). With the stock right at a strike at expiration, an option Gamma will be at its highest as the Delta will be potentially moving from 1.00 toward 0 or vice versa as the underlying crosses a strike. In these cases, the Gamma can be extremely high as the Delta changes rapidly with the underlying at the strike and expiration approaching.
Final Thoughts
Long option positions (net buying options) have positive (long) gamma. Positive gamma means we add gamma to the position’s delta when the underlying stock price increases, and subtract gamma from the position’s delta when the underlying stock price falls.
Short option positions (net selling options) have negative (short) gamma. Negative gamma means we subtract gamma from the position’s delta when the underlying stock price increases, and add gamma to the position’s delta when the underlying stock price falls.
The example of a gamma squeeze, even if they might be a bit overhyped nowadays, perfectly illustrates the importance of understanding gamma in options trading. It's a real-life example showing the power of gamma and the type of market moves it can fuel. The Gamma Risk is real, don't ignore it.
Like this article? Visit our Options Education Center and Options Trading Blog for more.
Related articles
- Options Trading Greeks: Gamma Explained
- Why You Should Not Ignore Negative Gamma
- Gamma Risk Explained
- Estimating Gamma For Calls Or Puts
- What Is Gamma Hedging And Why Is Everyone Talking About It?
- Market Neutral Strategies: Long Or Short Gamma?

There are no comments to display.
Join the conversation
You can post now and register later. If you have an account, sign in now to post with your account.
Note: Your post will require moderator approval before it will be visible.