SteadyOptions is an options trading forum where you can find solutions from top options traders. Join Us!

We’ve all been there… researching options strategies and unable to find the answers we’re looking for. SteadyOptions has your solution.

The Astonishing Story Behind XIV Debacle


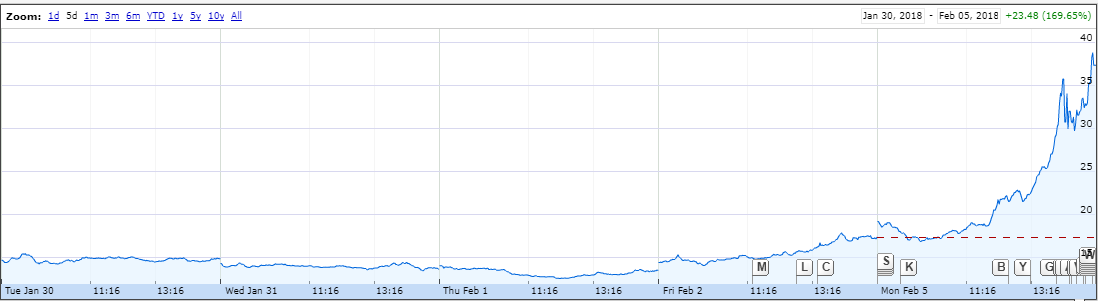
During the market's closing hour on Monday, February 5th, some sort of "flash crash," likely triggered by margin calls, attacked the CBOE Volatility Index (INDEXCBOE:VIX), also known as the "fear index." What was a bad day, turned into a never before seen move. Here is it: 

VIX2718.png


Whatever it was, the VIX went from 17% to 37% in a matter of two-hours, or up 115%. That is the largest percentage gain in the VIX in one day ever recorded. 


Even then, while that is a huge move, it wasn't really market disruptive in any great way other than, the market had a bad day. But then the after hours margin calls came in -- and that was an unmitigated disaster for one particular instrument of interest to us: Credit Suisse AG - VelocityShares Daily Inverse VIX Short Term ETN (NASDAQ:XIV). 

DON'T LISTEN TO TV 
The reporters on television have no understanding what XIV is -- it is not a naked short bet on VIX. No, it is an investment in the core underlying principle of market structures, driven by positive interest rates, known as Contango. 

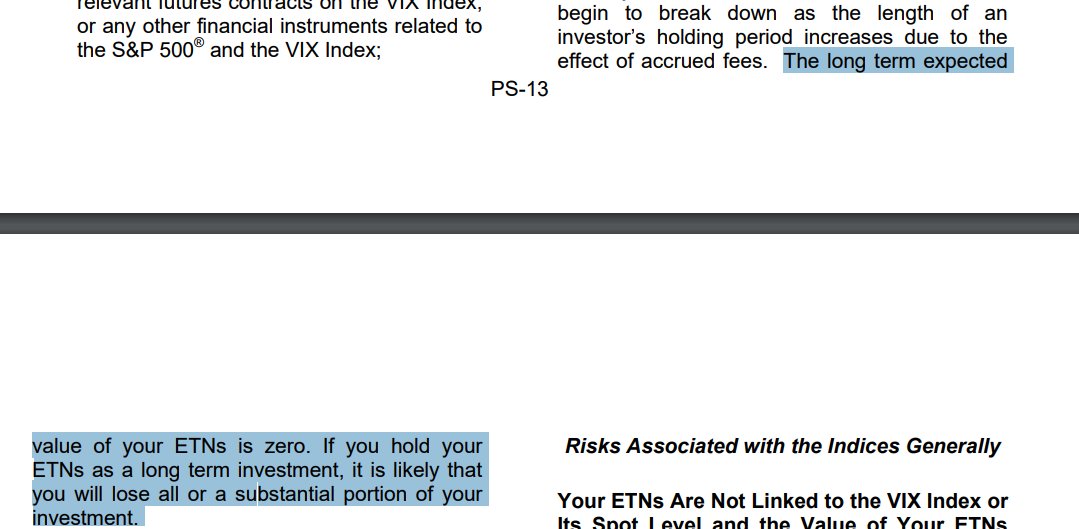
Remember, the XIV is the opposite of VXX, and the expected value of VXX is zero. Here it is, from the actual VXX prospectus: 
 

vxxzero.jpg


This instrument is not a radical short trade, it is fundamentally an investment in an ETN that reverses the value of an investment that is ultimately expected to be zero, which made it so good, for so long, and would have for several more decades. 

WHEN A LINE BECOMES THE FOCUS 
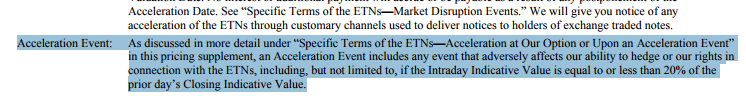
A little detail in the prospectus of XIV is that, hypothetically, should it lose 80% of its value from the close, it would cause a "acceleration event." That means that if the XIV sunk to 20% of its value, it would go to zero and the ETN would go away (and start over later). 

Now, obviously, this had never happened to XIV before, but it's only a decade old. When scientists back-tested XIV all the way back to the 1987 crash and including the 9/11 terror attacks, they noted that even then, XIV would not have suffered a 80% decline in a day. But we have never seen such a market with so many naked short vol sellers as we have today. 

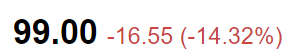
As a barometer, even as crazed as Monday was, here is how XIV closed: 
XIVclose2718.png


Down 14.32% is ugly, but, it's just a day -- a bad one, but nothing really all that crazed. Then the after hours session happened, and the best anyone can tell, as of this writing, is that some firm (or fund) had to unwind a short volatility position due to a margin call. 

That meant they had to buy the front month expiration of the VIX futures, leaving the second month unchanged. That little detail is everything, because the XIV is an investment on contango -- when the second month is priced higher than the first month. This is a market structure apparatus -- we could call it "normal market structure." 

But, with a flood of buying to cover short front month futures, the XIV started tumbling after hours. At first, social media saw it as a buying opportunity. Then it started dropping faster. Then disaster struck. 

The XIV dropped more than 80%: 
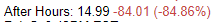
XIVah2718.png


The financial press did its best to cover it, but after a 2 minute segment on CNBC, there was nothing left to say because of one major rule inside the XIV prospectus. Here it is: 
 

xivacc.png


In that fine print, it reads that if the value of XIV dips to 20% of the closing value (if it is down 80%), the fund stops. That is, since this trade, if done with actual futures contracts, can actually go negative, the ETN stops itself out at a 80% one day loss. This is why we investors use the ETN, knowing that a 100% loss is the worst that can happen, as opposed to the futures, where much worse than 100% loss can occur. 

And the greatest burn of it all 
As of Tuesday morning the VIX is down huge (of course it is), the market structure has held (of course it did), and XIV would be having a very good day (of course it would). 

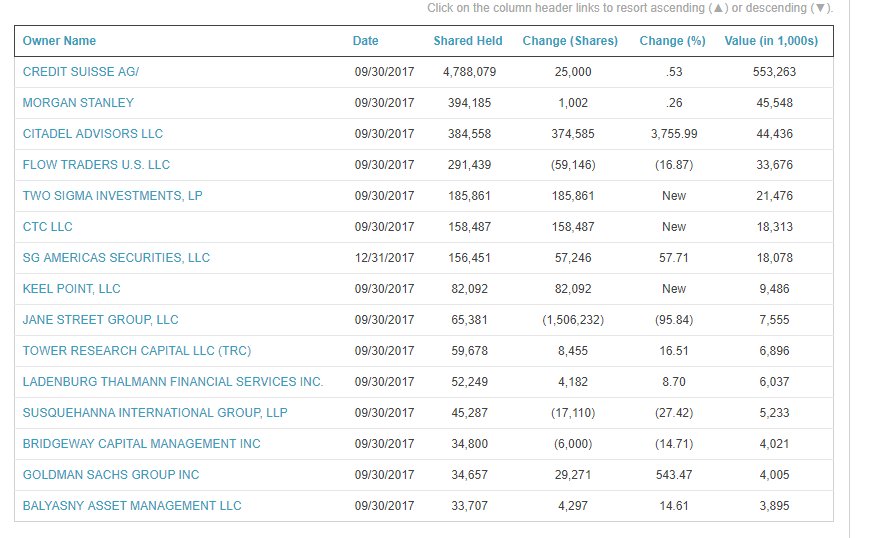
But, worse --- it turns out, as far as we know (still speculation), while it's hard to swallow, that the unwinding was done by none other than Credit Suisse itself. Yes, the creators of the ETN had another concern, beyond the assets under management -- and here it is -- -- look at the largest shareholder. 
 

xivholders.jpg

Credit Suisse quietly became the single largest holder of the very instrument it created, and by a huge amount. So, as 4pm EST came around, a bad day in XIV, but survivable, became the death knell, because the largest holder, the XIV's custodian, panicked, and covered. 

But, Credit Suisse could not very well just sell millions of shares of XIV in a thinly traded after hours session, so it turned to the VIX futures market. 

It appears, as of this writing, that this has actually occurred. While Credit Suisse (the issuer of the ETN) has yet to comment, it appears that whatever this "flash crash" did, whatever margin calls were triggered after hours, the short vol trader was in fact the firm -- it unwound positions in a size that the market has never seen before, and that means that it looks like XIV is possibly going to some very, very low number -- like $0, low. 

It's with great regret that as of right now, we do believe XIV is, for all intents and purposes, gone, from a little rule hidden deep in the prospectus that no one gave much concern and that got blasted away when the top holder in the note was the custodian itself. 

It's a reminder that the real danger to a portfolio is not a bear market -- we recover from those quite nicely as a nation -- it's the delirium that happens when a bull market gets totally out of control and margin is used excessively in a spurt of just a few days. And by margin, we don't mean normal, everyday investors, we mean the institutions -- even the ones we entrust to be custodians of our investments. 

So that's it. XIV likely would have done just fine after this moment in time in the market, will not be given that opportunity to recover. It has been blown out on the heels of yet another Wall Street debacle, which no one seems to even understand, yet. 

The author is long shares of XIV in a family trust. 

Ophir Gottlieb is the CEO & Co-founder of Capital Market Laboratories. He contributes to Yahoo! Finance, CNNMoney, MarketWatch, Business Insider, and Reuters. This article was originally published here.
What Is SteadyOptions?

12 Years CAGR of 114.5%

Full Trading Plan

Complete Portfolio Approach

Real-time trade sharing: entry, exit, and adjustments

Diversified Options Strategies

Exclusive Community Forum

Steady And Consistent Gains

High Quality Education

Risk Management, Portfolio Size

Performance based on real fills

Subscribe to SteadyOptions now and experience the full power of options trading!
Subscribe

Non-directional Options Strategies

10-15 trade Ideas Per Month

Targets 5-7% Monthly Net Return

Visit our Education Center

Recent Articles

Articles

  • Options Trading Risk Management: Position Sizing, Drawdowns, Portfolio Diversification

    What do you think matters most in financial markets? Even with years of experience, a good strategy, and plenty of capital, you can still lose a lot of money if you don’t manage your risk. Uncertainty is part of what makes financial markets interesting, and every trader or investor has to deal with it.

    By Naoufal Seddik,

    • 0 comments
    • 136 views
  • Your 30-Delta Put Is Not a 30% Chance

    What four option chains say about delta as odds, and what it means for strangles and the wheel

    A quick question before we start. You sell a 30-delta put on a volatile stock with about a month to expiry. What is the chance that it finishes in the money? Keep your answer in mind.

    By Nikolai Alexander,

    • 0 comments
    • 278 views
  • M: one green row, and what TGT had to do with it

    Yesterday I opened M's Straddle page. M reports Dec 2 before the open, so Dec 1 is the last day to hold. One row of the History Matrix stood out in https://earningsstudy.com/ tool: entering at T-9 was green on every exit, while almost everything around it was red. Across all 78 entry and exit pairs, the typical one returned −2.0%. The T-9 row ran from +1.1% (out the next day) to +22.2% (out at T-3), and +9.5% held to T-0.

    By krisbee,

    • 0 comments
    • 338 views
  • AI In Options Trading: Could It Change The Way You Trade?

    Have you ever imagined handing your trading strategy to an AI system that could analyze markets, backtest your rules, and execute trades for you? Today, with the right data and tools, that’s possible. AI can help you analyze markets, backtest a strategy across years of data, calculate risk, and even optimize your portfolio.

    By Naoufal Seddik,

    • 0 comments
    • 1456 views
  • 5 Stocks For Options Trading In November 2026

    S&P 500 companies lost nearly $3 trillion in market value on November 5. The S&P 500 fell 4.36%, the Nasdaq Composite fell 5.52%, and the Dow lost 3.44%. The Russell 2000 was down more than 4%. Investors were already wondering if all the money tech companies were spending on AI would pay off.


    By Naoufal Seddik,

    • 0 comments
    • 2635 views
  • What the Gamma Map Said Before Nine Bullish Combos

    In mid-September SteadyOptions added a new structure to the model portfolio: the earnings bullish combo, a call debit spread paired with a narrower put debit spread as a hedge, opened ahead of earnings and closed before the report. 

    By krisbee,

    • 0 comments
    • 7201 views
  • Delta-Neutral Options Strategies for Earnings

    Most options trading starts with a directional guess: you think a stock goes up, so you buy calls. But some of the most reliable earnings strategies don't require you to be right about direction at all. They're built to profit from volatility itself — from how much a stock moves, or from the collapse of implied volatility after the report — while staying largely indifferent to which way it goes.

    By krisbee,

    • 0 comments
    • 10410 views
  • The Last 14 Minutes: Why We Stopped Looking at Options Closing Prices

    Here is a puzzle from our own earningsstudy charts. On Thursday, August 6, the ADBE one-week put calendar — the same 260 strike, the same September 11/18 expirations — was worth $1.425 at 3:46pm and $2.60 at the 4:00pm close. Nothing happened to the trade in those fourteen minutes.

    By krisbee,

    • 2 comments
    • 7121 views
  • Expanded Trading Hours for Select Equity Options

    The Cboe Options Exchange will start offering expanded trading hours for select high-liquidity single-stock equity options. The schedule features a morning Global Trading Hours (GTH) session from 7:30 a.m. to 9:25 a.m. ET and an afternoon Curb session from 4:00 p.m. to 4:15 p.m.

    By Kim,

    • 0 comments
    • 2306 views
  • How LEAPS Differ From Short-Term Options

    LEAPS stands for Long-Term Equity Anticipation Security. Which is just a long-dated option, typically referring to those with expirations more than a year out. There’s no technical difference between LEAPS and shorter-term options other than the expiration date. They’re traded on the same exchanges and have the same rules surrounding margin and whatnot.

    By Pat Crawley,

    • 0 comments
    • 33264 views

  Report Article


We want to hear from you!


Over the long term, shorting volatility is still a winning strategy. The key is position sizing. Check out our performance - VXX and SVXY trades are still very positive, despite the last two losers. But we are doing reduced position sizing (5% instead of 10%) due to higher risk.

Share this comment


Link to comment
Share on other sites

But what’s troubling about Ophir’s article is that it’s not the market that determined the fate of XIV/SVXY but a single rogue player with huge monetary influence.  There’s no way to rationally play the odds in such an environment- is there? 

Share this comment


Link to comment
Share on other sites

4 hours ago, NikTam said:

But what’s troubling about Ophir’s article is that it’s not the market that determined the fate of XIV/SVXY but a single rogue player with huge monetary influence.  There’s no way to rationally play the odds in such an environment- is there? 

I think our SVXY collar proves that you can still make money if you know what you are doing.

Share this comment


Link to comment
Share on other sites

15 minutes ago, Kim said:

I think our SVXY collar proves that you can still make money if you know what you are doing.

Yes, I like the collar strategy.

Share this comment


Link to comment
Share on other sites


Join the conversation

You can post now and register later. If you have an account, sign in now to post with your account.
Note: Your post will require moderator approval before it will be visible.

Guest
Add a comment...

×   Pasted as rich text.   Paste as plain text instead

  Only 75 emoji are allowed.

×   Your link has been automatically embedded.   Display as a link instead

×   Your previous content has been restored.   Clear editor

×   You cannot paste images directly. Upload or insert images from URL.

Loading...