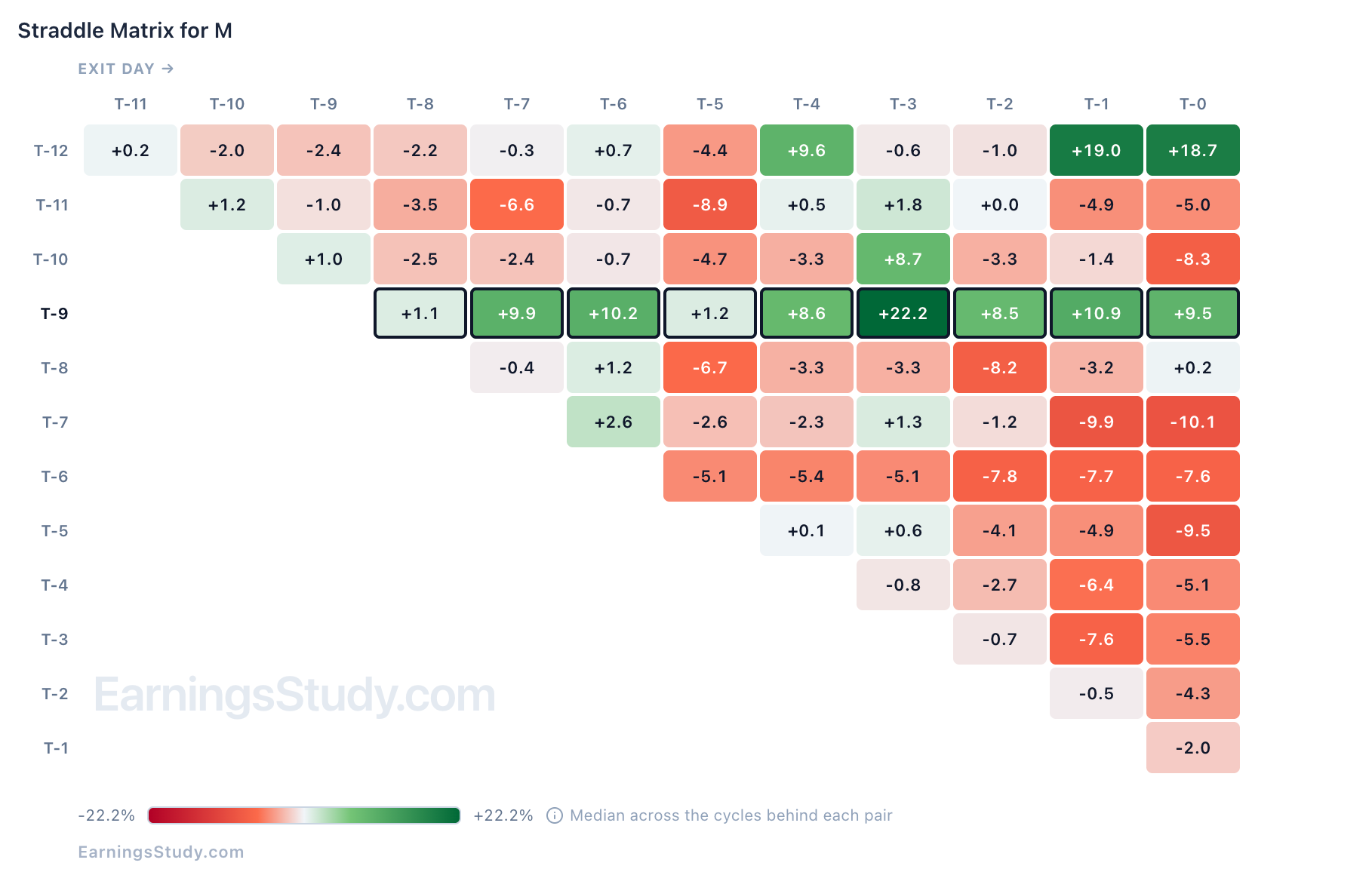
M Straddle History Matrix, median return, 8 cycles. Yesterday's T-9 row outlined for this post.
A row like that usually has a reason. Here's how I went looking for it.
1. The low point on the RV chart. The black median line on the Straddle RV chart dips at T-9: 10.60%, against 11.43% at T-10 and 11.51% at T-8. In past cycles, T-9 was the day M's straddle was cheapest relative to the stock. Yesterday's reading was 10.60%, right on that median.
2. Peer earnings markers. Above the RV chart, Peer earnings marks where a peer's report fell in each of M's past cycles. M's peer list only has KSS, so I chose Custom and typed TGT. The red stars tell the story. In Jun 2026, Dec 2025 and Sep 2025, TGT's last session before its report landed on M's T-9. It did again this cycle: TGT reported this morning, Nov 18, before the open. Entering M at T-9 meant entering the night before a major peer reported.
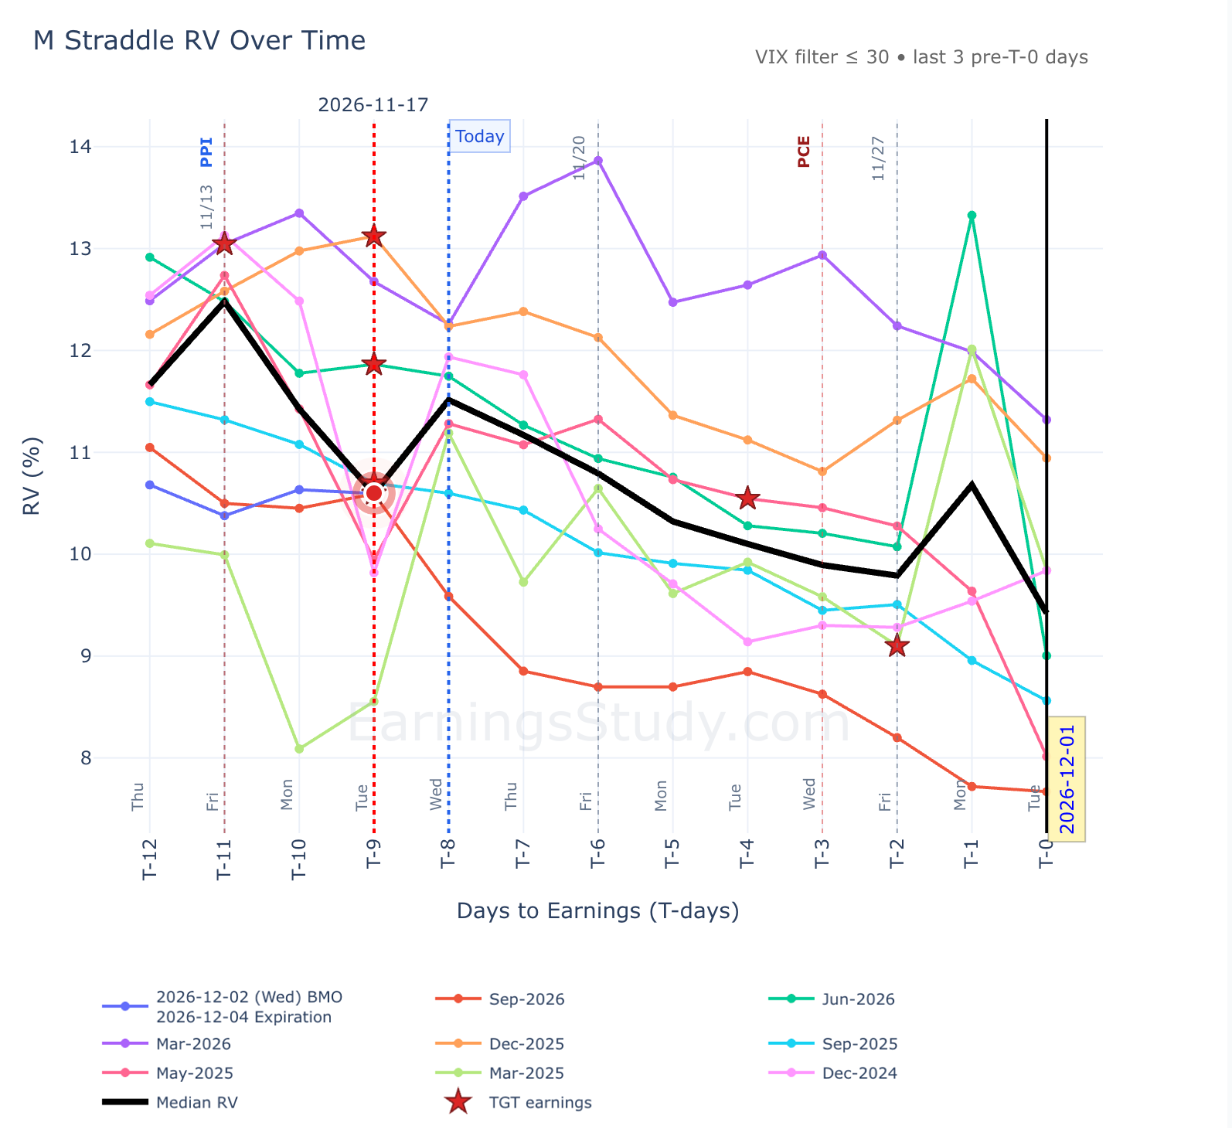
M Straddle RV with TGT earnings marked (stars). EOD data through Nov 17.
3. Check it cycle by cycle. Hover any cell to see the cycles behind it. For T-9 to T-3, the two biggest winners were Jun 2026 (+67.5%) and Dec 2025 (+48.8%), both cycles where TGT reported right after T-9. The third, Sep 2025, was flat (−0.7%). TGT isn't the whole story either: Mar 2025 (+47.8%) and May 2025 (+29.2%) did well without it, and Sep 2026 lost 18.4%. The peer report tipped the odds; it didn't guarantee anything. One more detail: in the TGT cycles the gain mostly didn't arrive overnight. T-9 to T-8 was +4.4%, −7.2% and −2.2%, and the gain built over the following week.
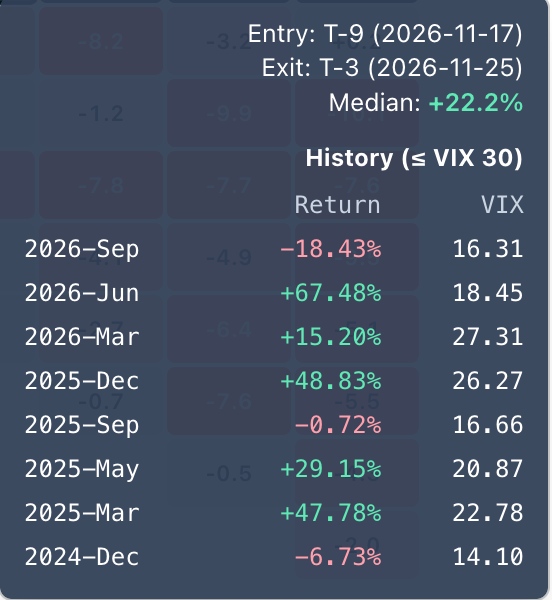
Cycles behind T-9 → T-3 (hover any cell).
4. Plan the exit before you enter. Switch the matrix to Reached target and pick +20%. From a T-9 entry, 3 of 8 cycles reached +20% by the very next day, and 5 of 8 had reached it by T-4. That's where a GTC profit order would have filled.
This cycle. The Trade Details card showed the Dec 4 $23.50 straddle at $2.49 at yesterday's close. After TGT reported this morning, the same straddle was trading around $2.96, up about 19% in a day. A +20% GTC from $2.49 would sit at $2.99.
Now look at today's row. Enter at T-8, after TGT has already reported, and the row turns red again. The best exit is +1.2% at T-6, and only 2 of 8 cycles ever reached +20%. The setup was the day before the peer reported, not the day after.
To do this on any name:
- Look for a row or column that doesn't match its neighbors.
- Check the RV chart for a dip on that day.
- Use Peer earnings (or Custom) to see whether a peer's report lines up.
- Hover the cells to see which cycles carried it.
- Use Reached target to choose a realistic GTC before you enter.
A caution: this rests on 8 cycles, and only 3 of them had TGT at T-9. Treat it as a reason to look, not a rule. Peer dates shift from cycle to cycle, so check where the star sits in the current cycle before relying on it.
Educational research only, not trade advice. Based on EOD data; past cycles don't guarantee future results.
EarningsStudy research tool is SteadyOptions official partner.
And this is how one of our mentors @rasar took advantage of the information presented by the tool:
This ☝️ is worth it's weight in gold. With a little effort (a fraction of what we used to do earlier), I'm able to distill large volumes of data into meaningful and information. I kind of used a small subset of what you did here to validate my COST trades, and am finding it quite handy - cuts a lot of time spent correlating and analyzing stuff manually.
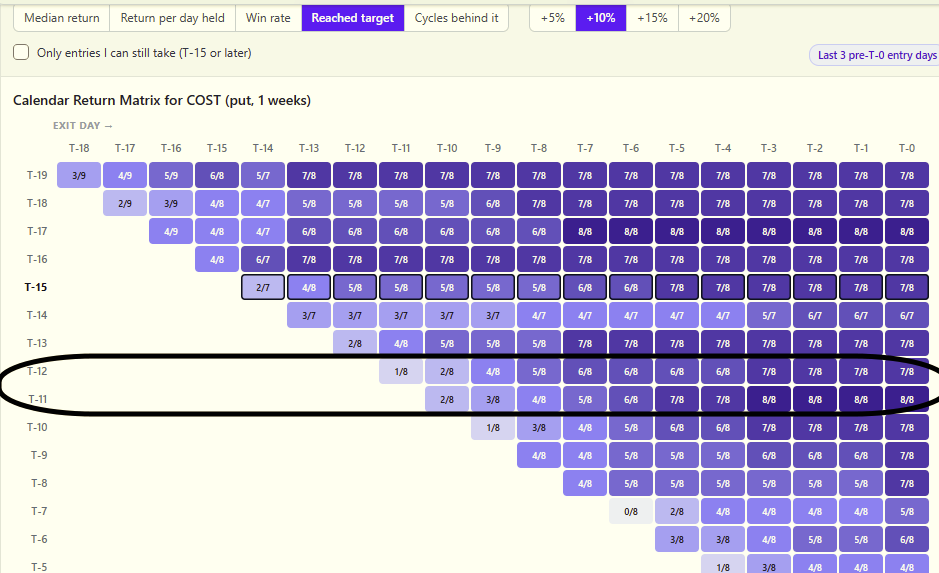
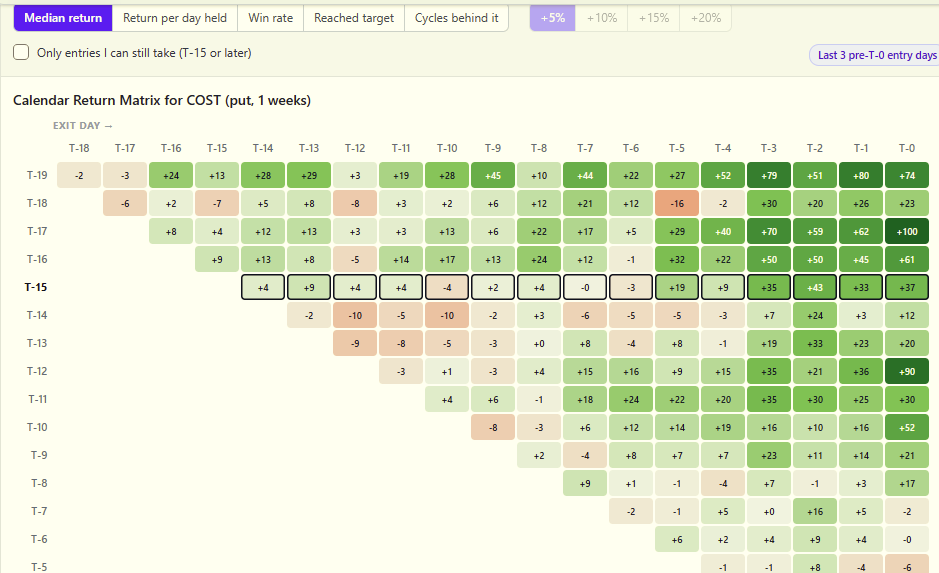
I opened on T-17 and T-16 because of the attractive return and "reached target" matrices. As it turned out, I closed the trades on the same or next day because my target ~30% was reached. But the matrices still seem attractive.
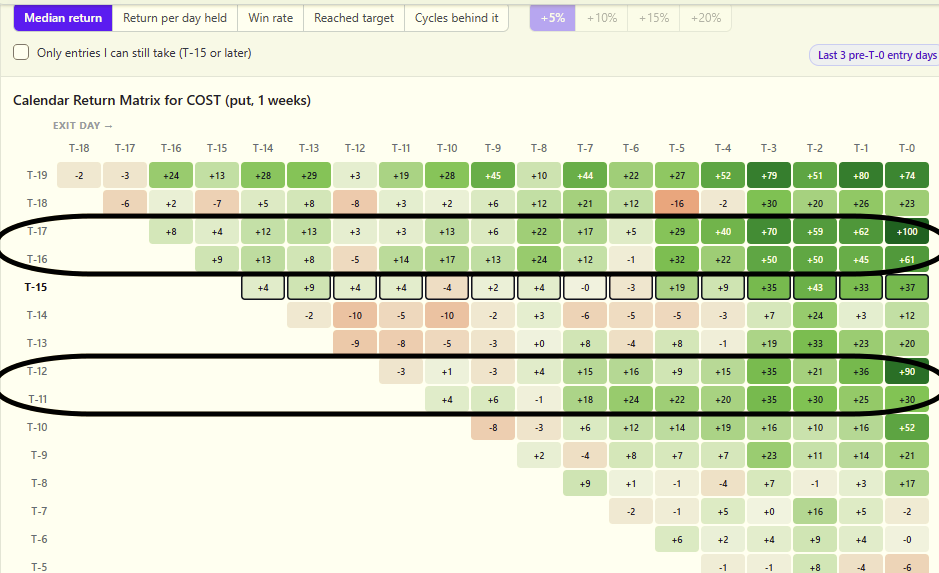
I re-opened the trade today (T-15), even though the trade isn't expected to achieve the same return in the short term. I'll likely close it targeting a 10%+ return tomorrow and free up some capital.
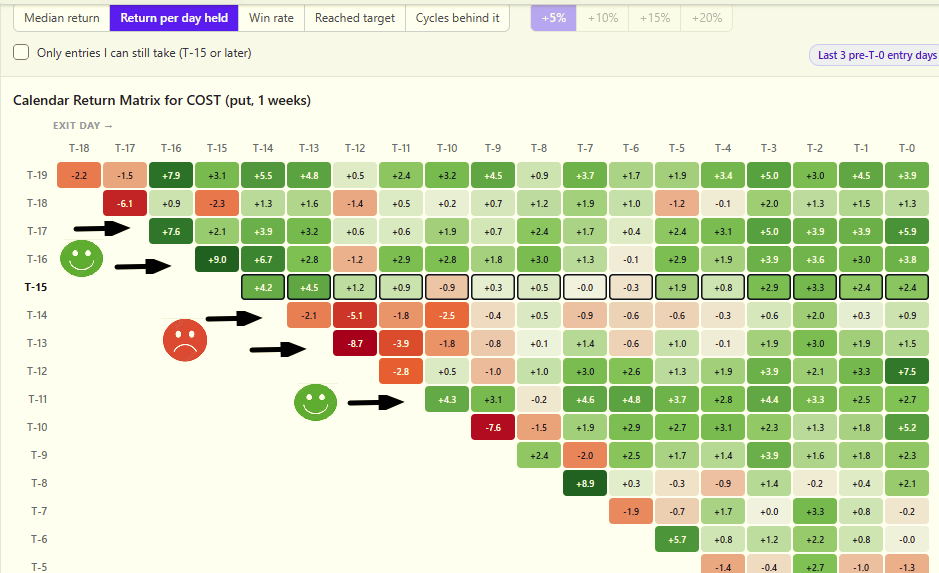
Entry on T-14, T-13 is not as attractive based on the win rate and other matrices. I would need to hold for a longer period to achieve decent return. So I'll probably hold off re-opening.
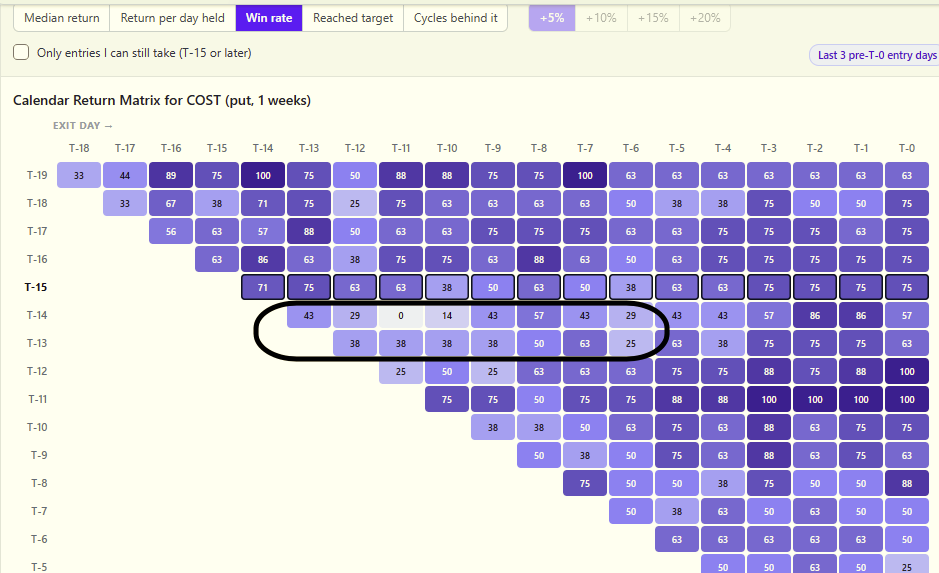
T-12 thru T-11 - Looks better, with larger gain if held to T-0, otherwise decent win rate and consistent gains for in-out trades. T-11 (24 November) seems optimal for reentry; the "Return per day held" matrix shows ~4% gain per day, giving me a wide choice of days to exit.
Thanks for the tool - it adds a whole new dimension to SO trading, almost to the point of making homework fun.


There are no comments to display.
Join the conversation
You can post now and register later. If you have an account, sign in now to post with your account.
Note: Your post will require moderator approval before it will be visible.