Leaderboard


Popular Content
Showing content with the highest reputation since 11/14/26 in Posts
-
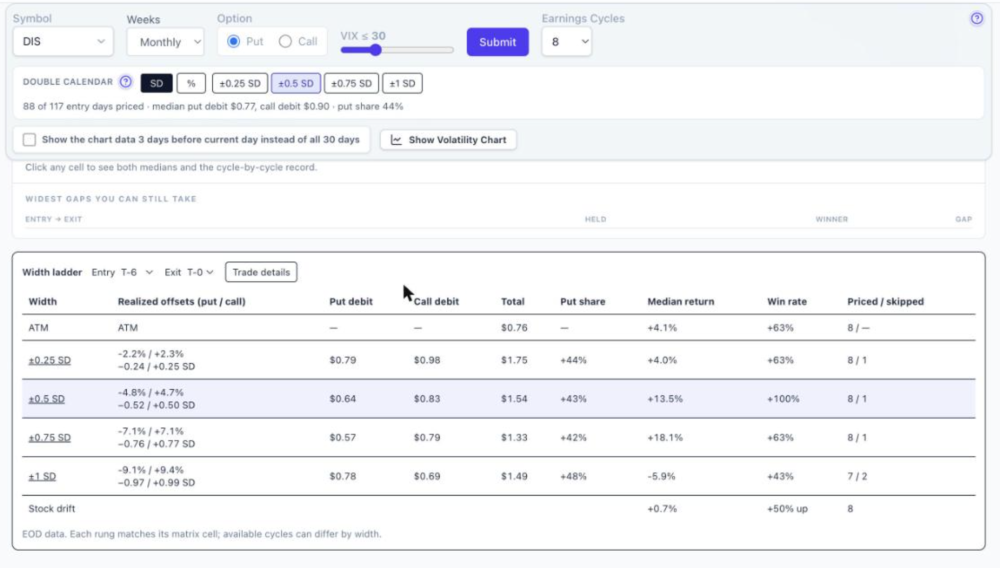
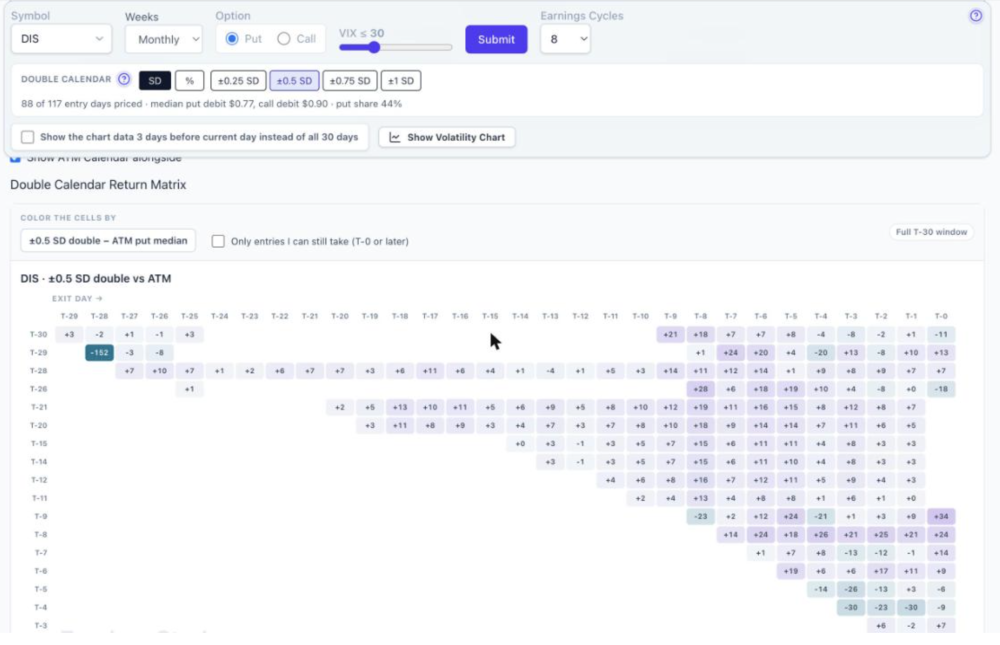
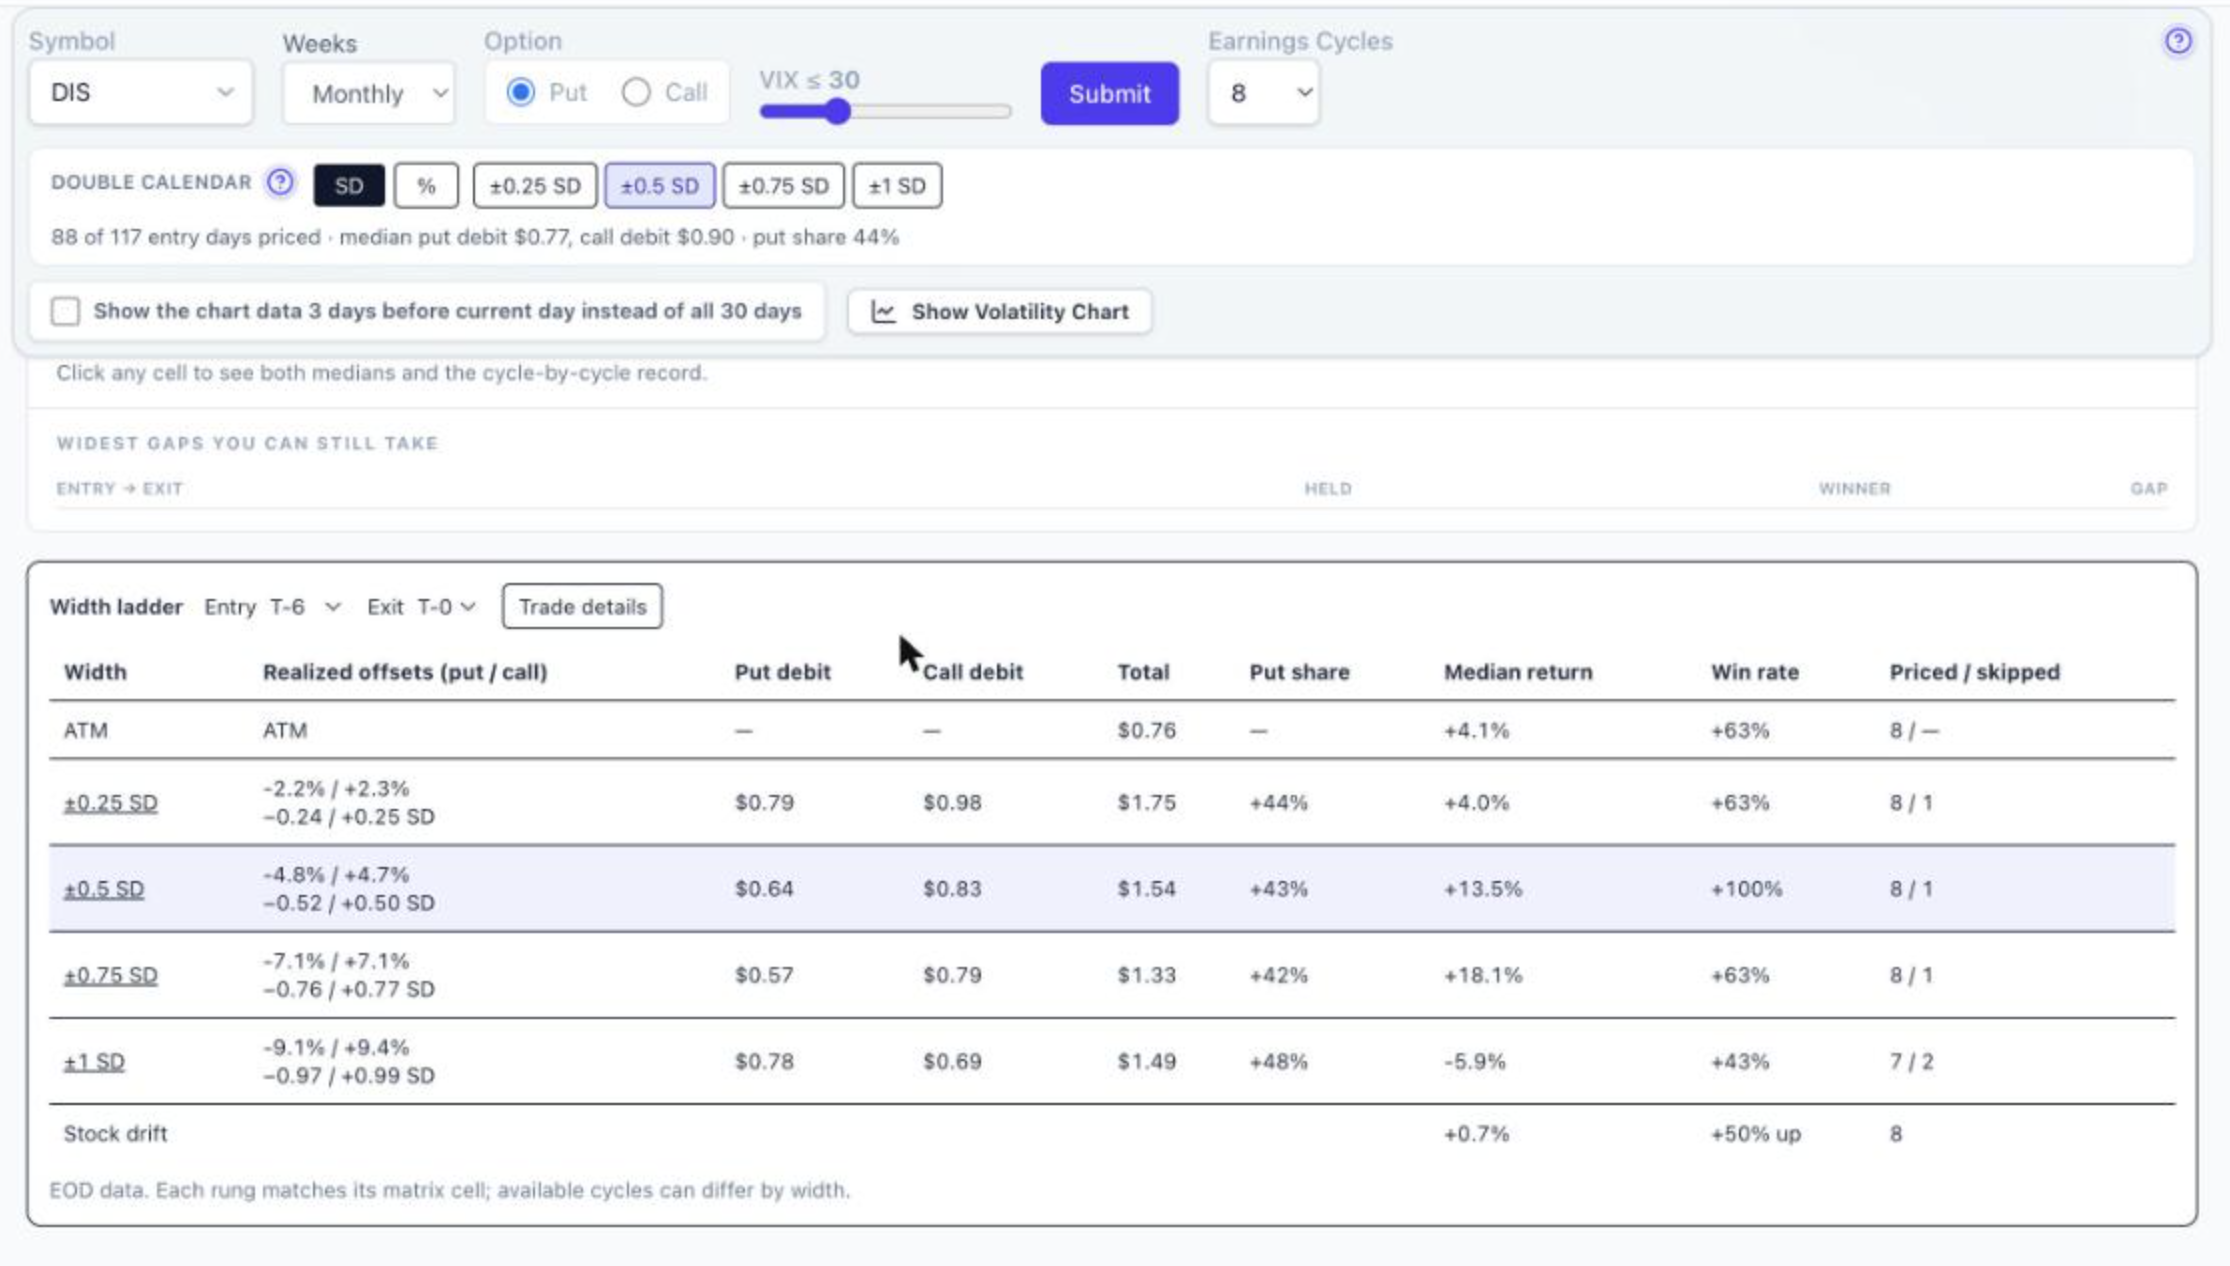
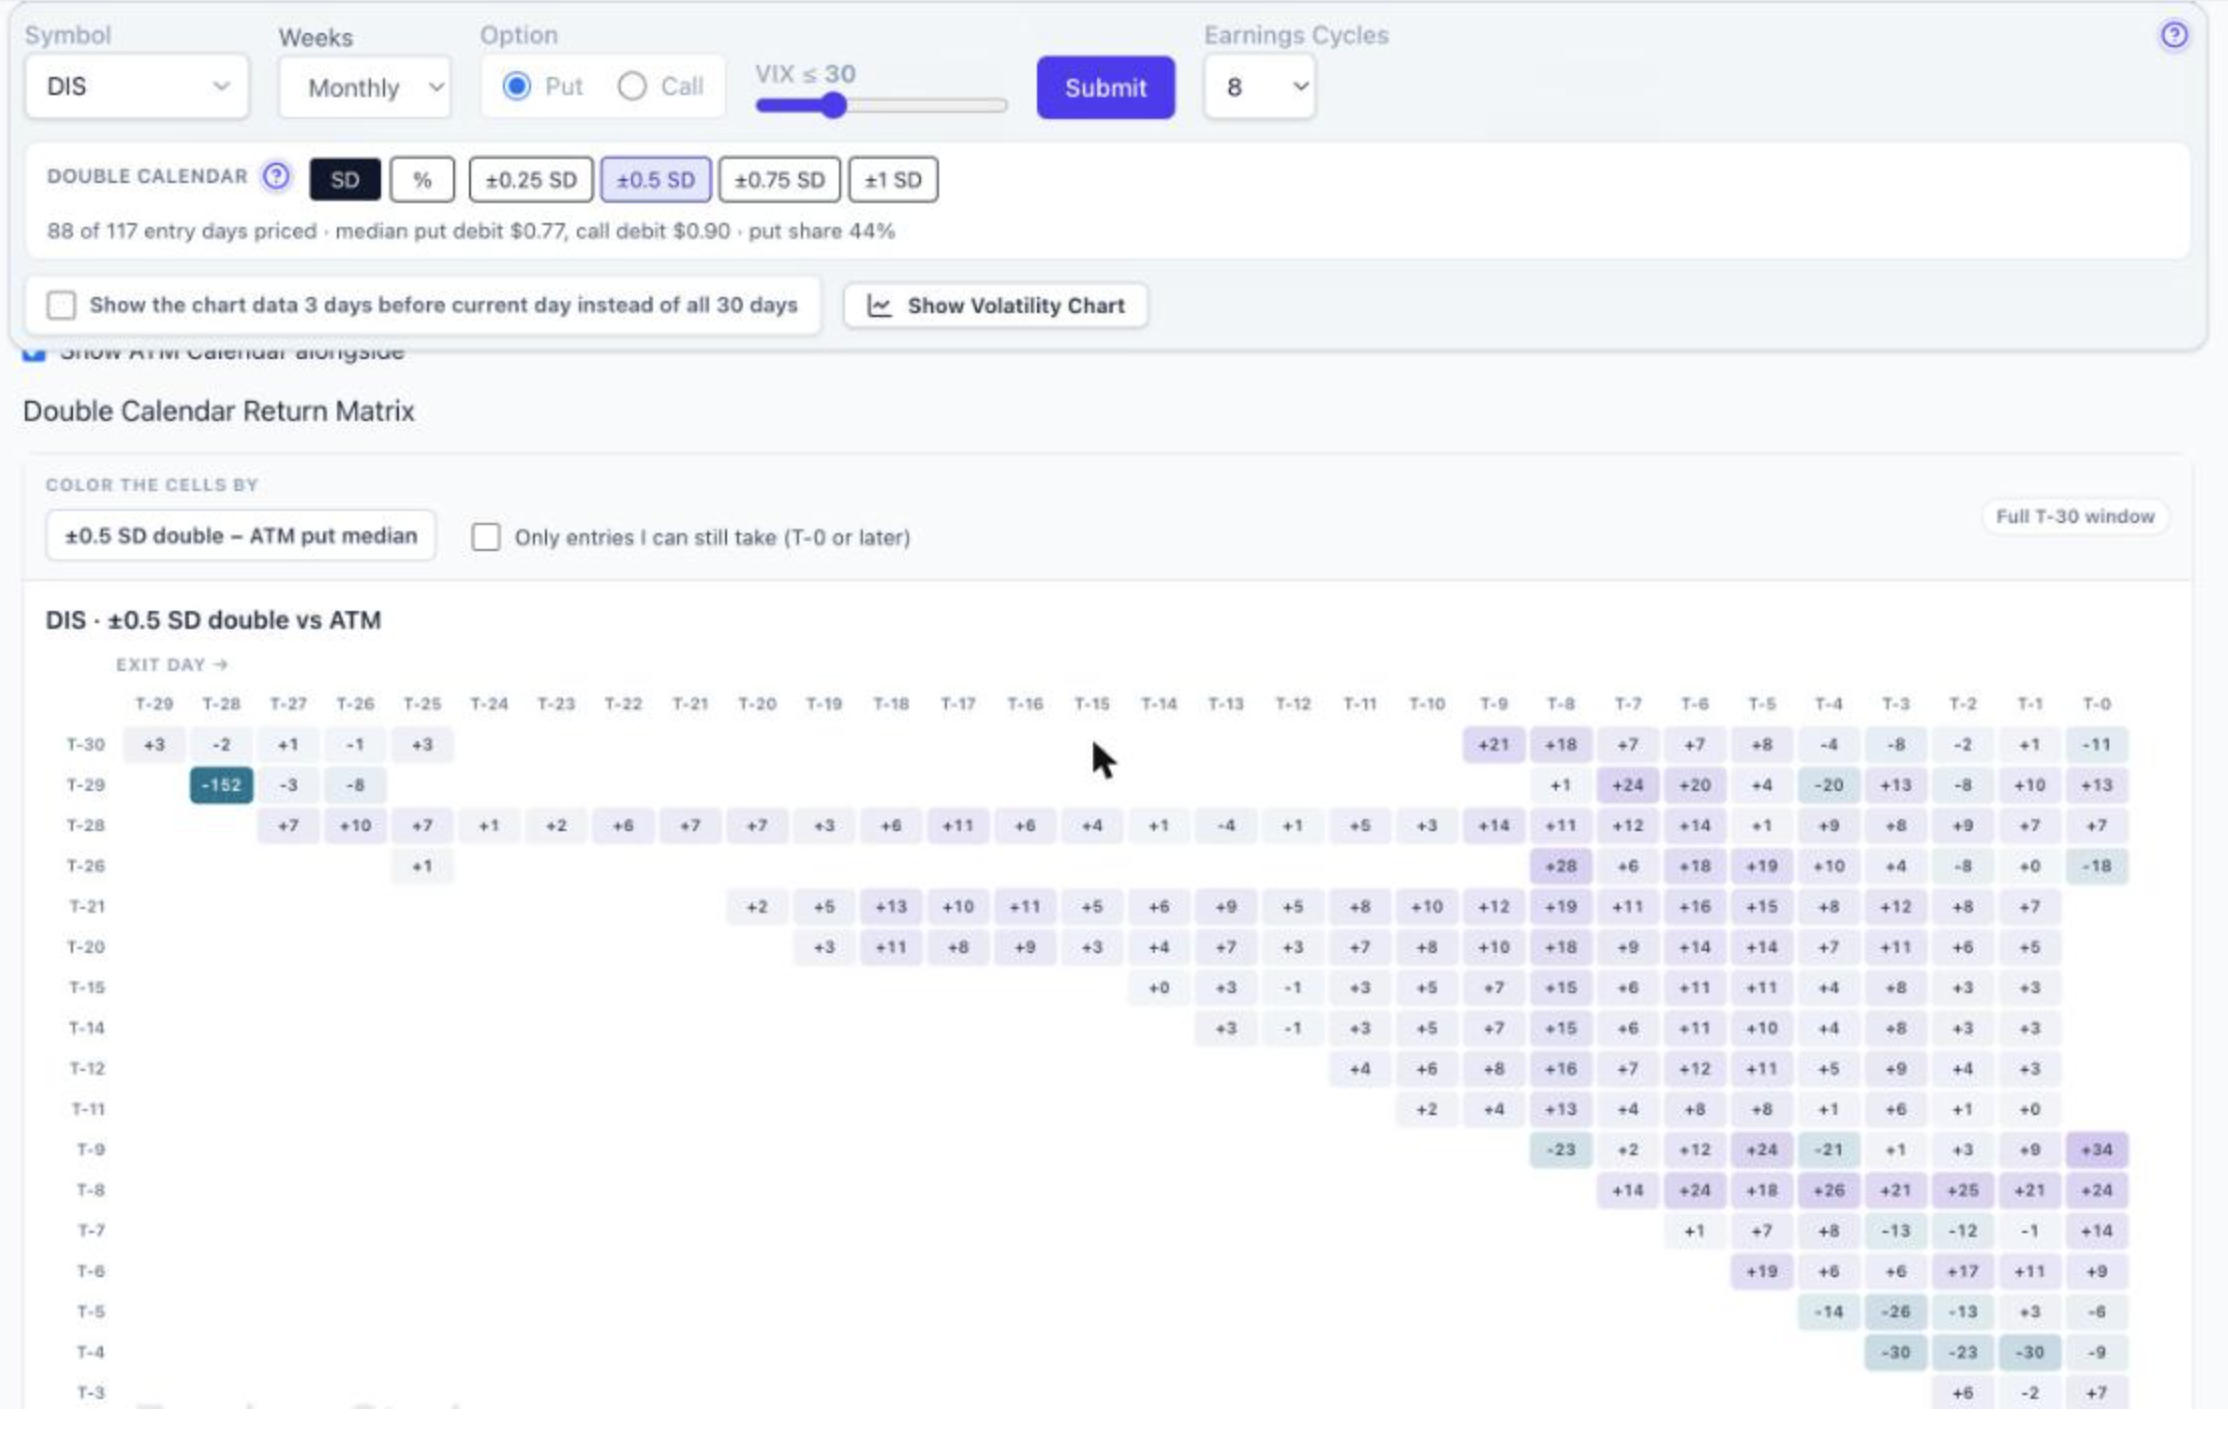
1. If the ATM calendar is profitable, is the DC profitable on the same trade? Usually, but not always, and the reverse is also true. Both structures are long the same thing: the front-month IV rising faster than the back month as earnings approach. That lifts both. Where they part ways is the stock. If the stock sits still, the ATM calendar collects the full peak and the DC collects less. If the stock drifts a few percent before the report, the ATM calendar gives back its gain while the DC is still inside its profit zone. So “ATM wins” and “DC wins” overlap most of the time, and the exceptions go both directions. You can see this for any symbol on the Double Calendar page by ticking “Show ATM Calendar alongside.” The grid then shows, for every entry/exit pair, which one did better and by how much. Here’s DIS: Purple is where the ±0.5 SD double beat the ATM put calendar, teal is where ATM won. Most of the grid is purple for DIS, but T-9 → T-9/T-10 and the T-4/T-5 entries are teal. Same symbol, same data, the answer depends on the window. 2. ATM expands more, so why start with DC? Because you’re trading peak for consistency. The width ladder under the matrix prices the same entry/exit window at every width, so the trade-off is visible instead of assumed. DIS, enter T-6, exit T-0: ATM: +4.1% median, 63% win rate. ±0.5 SD double: +13.5% median, 100% win rate across 8 cycles. On this name the DC didn’t just win more often, it also returned more, because DIS tends to drift before earnings. On AMAT the same ladder shows the opposite shape: ATM +15% median with 75% wins, ±0.5 SD +8% with 86% wins. That’s the honest answer to “why start with DC”: on some names it’s a smaller edge with fewer losers, on others it’s simply the better trade, and on wide widths (±1 SD) it’s often worse than ATM. The ladder tells you which case you’re in. 3. With a DC, one calendar loses as the stock moves and you hope the other compensates. No guarantee? Correct, there’s no guarantee, and I’d put it slightly differently. The DC isn’t two separate bets where one hedges the other. It’s one position with a wider profit zone and a dip in the middle. When the stock moves toward one strike, that calendar gains (it’s becoming the ATM calendar) while the other loses, and the IV build lifts both. Whether the net is positive depends on how far the stock moves relative to where the strikes were set. That’s why width matters so much: ±0.5 SD on DIS has a 100% win rate in that window, ±1 SD on the same name has 43%. Too wide and the strikes are so far out that the structure becomes a bet on direction. There’s nothing guaranteed about any of these; what the page gives you is the historical distribution so you aren’t guessing. 4. The earnings calendar depends on RV expansion, not like a regular calendar. Agreed, and that applies to the double exactly as it applies to the single. Both calendars in the DC are long vega on the same term structure; the debit curve at the top of the Double Calendar page rises into earnings the same way the single-calendar RV chart does, for the same reason. The DC just doesn’t need the stock to stay pinned to one strike to keep that expansion. Short version: the DC is not a better calendar, it’s a different point on the peak-versus-consistency line, and whether it’s the right point depends on the symbol and the window. Check the ladder and the ATM-alongside grid for the name you’re looking at before deciding. Two notes for you, not for the post: the DIS numbers are from the page as of the 11/13 close with DIS now at T-0, and both screenshots are with “Show the chart data 3 days before current day” unchecked so the full T-30 window shows. If you’d rather keep the reply shorter, item 4 can be cut without losing anything.
 2 points
-
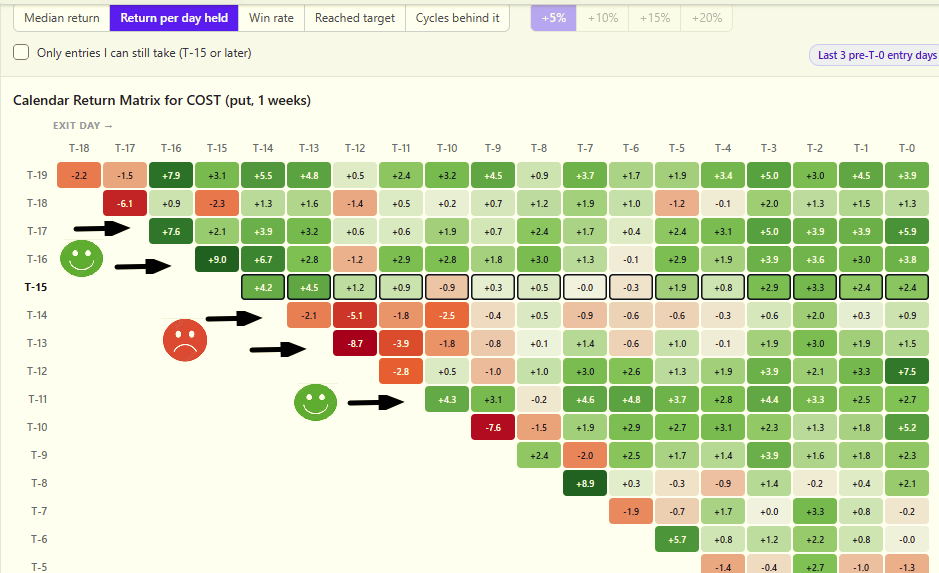
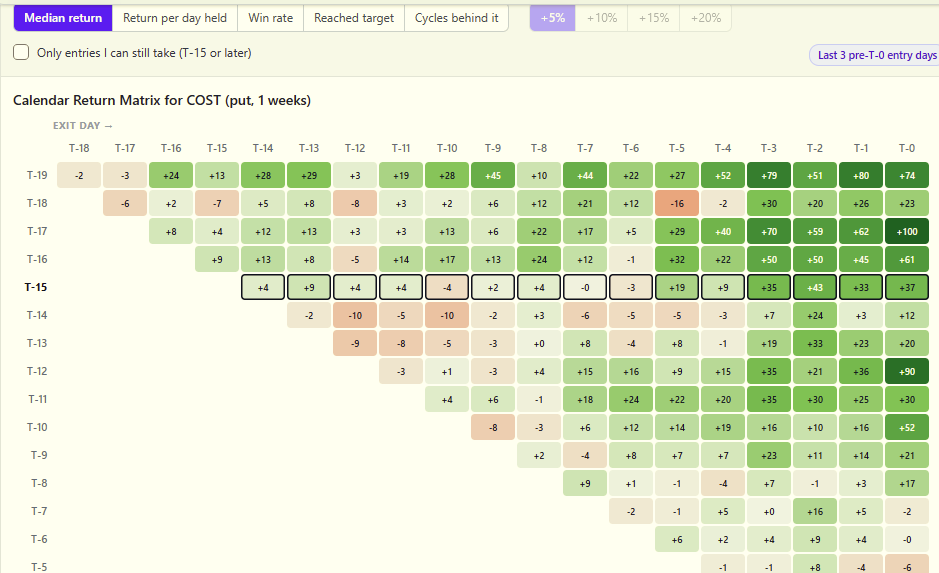
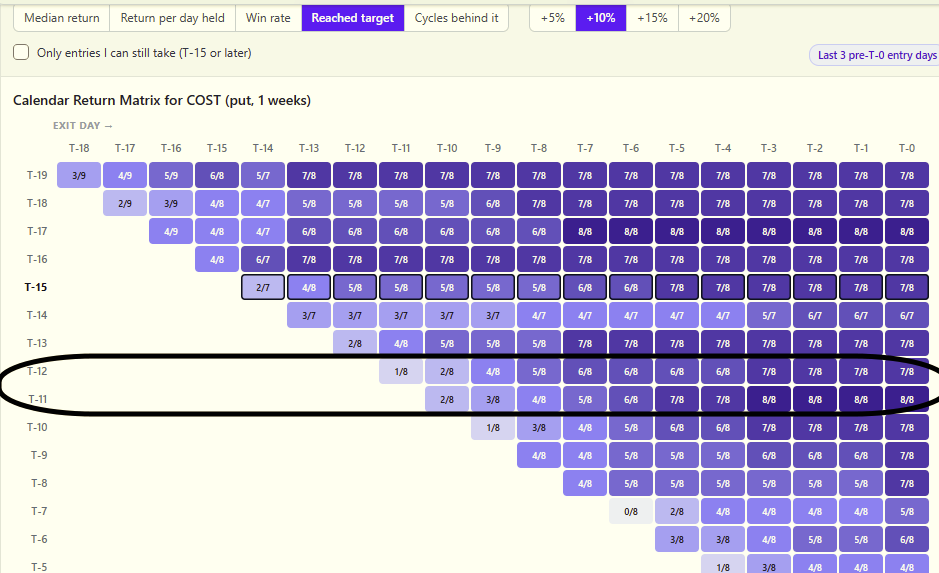
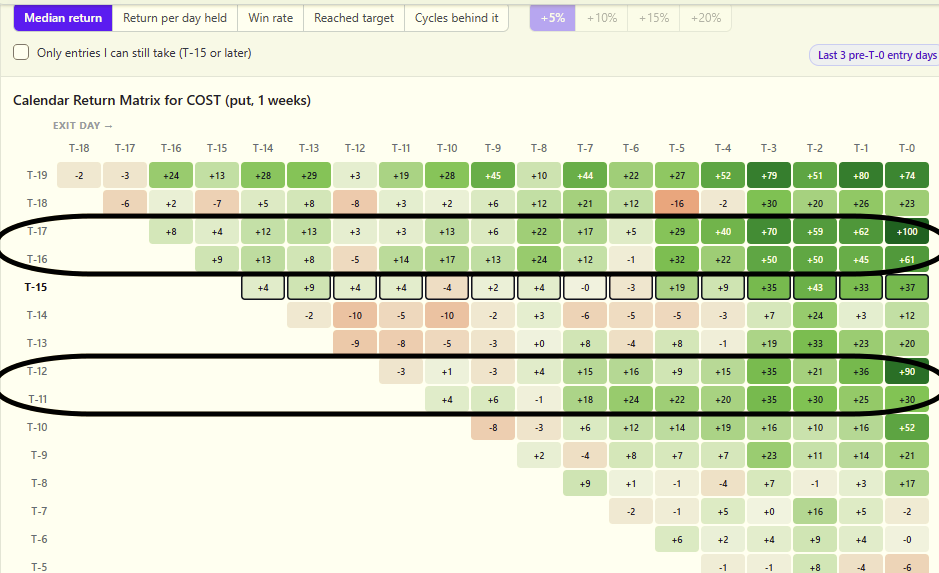
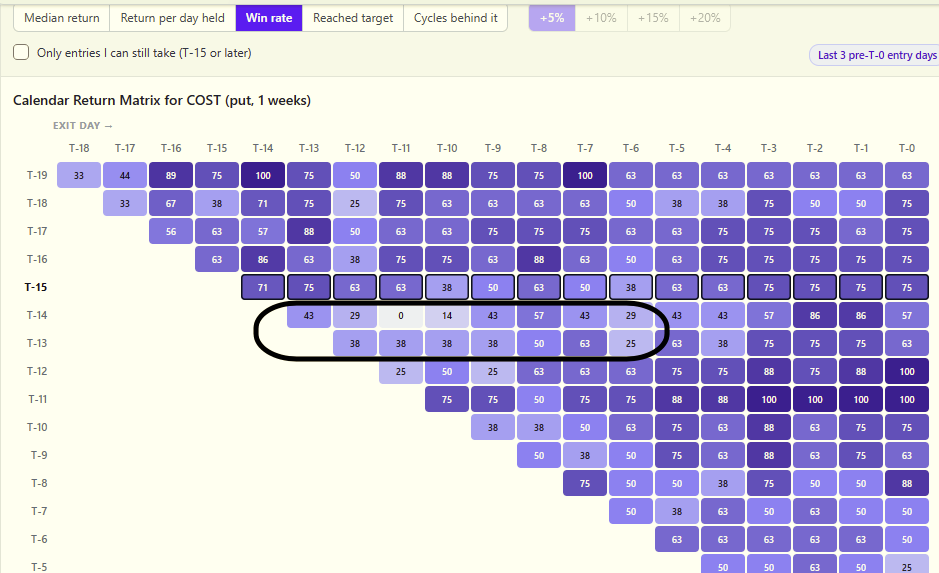
This ☝️ is worth it's weight in gold. With a little effort (a fraction of what we used to do earlier), I'm able to distill large volumes of data into meaningful and information. I kind of used a small subset of what you did here to validate my COST trades, and am finding it quite handy - cuts a lot of time spent correlating and analyzing stuff manually. I opened on T-17 and T-16 because of the attractive return and "reached target" matrices. As it turned out, I closed the trades on the same or next day because my target ~30% was reached. But the matrices still seem attractive. I re-opened the trade oday (T-15), even though the trade isn't expected to achieve the saame return in the short term. I'll likely close it targeting a 10%+ return tomorrow and free up some capital. Entry on T-14, T-13 is not as attractive based on the win rate and other matrices. I would need to hold for a longer period to achieve decent return. So I'll probably hold off re-opening. T-12 thru T-11 - Looks better, with larger gain if held to T-0, otherwise decent win rate and consistent gains for in-out trades. T-11 (24 November) seems optimal for reentry; the "Return per day held" matrix shows ~4% gain per day, giving me a wide choice of days to exit. Thanks for the tool - it adds a whole new dimension to SO trading, almost to the point of making homework fun.
 1 point
-
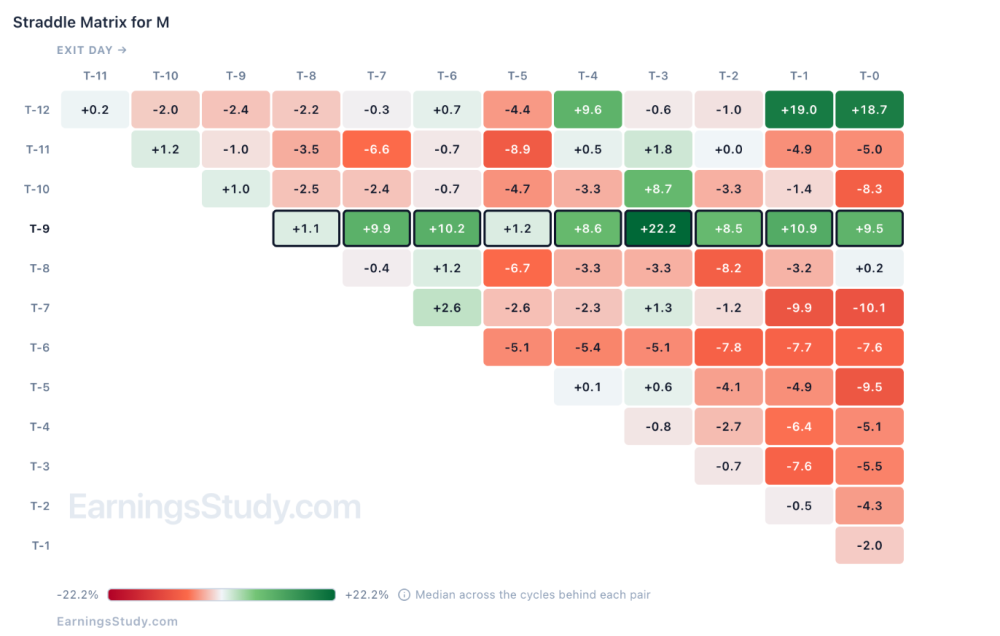
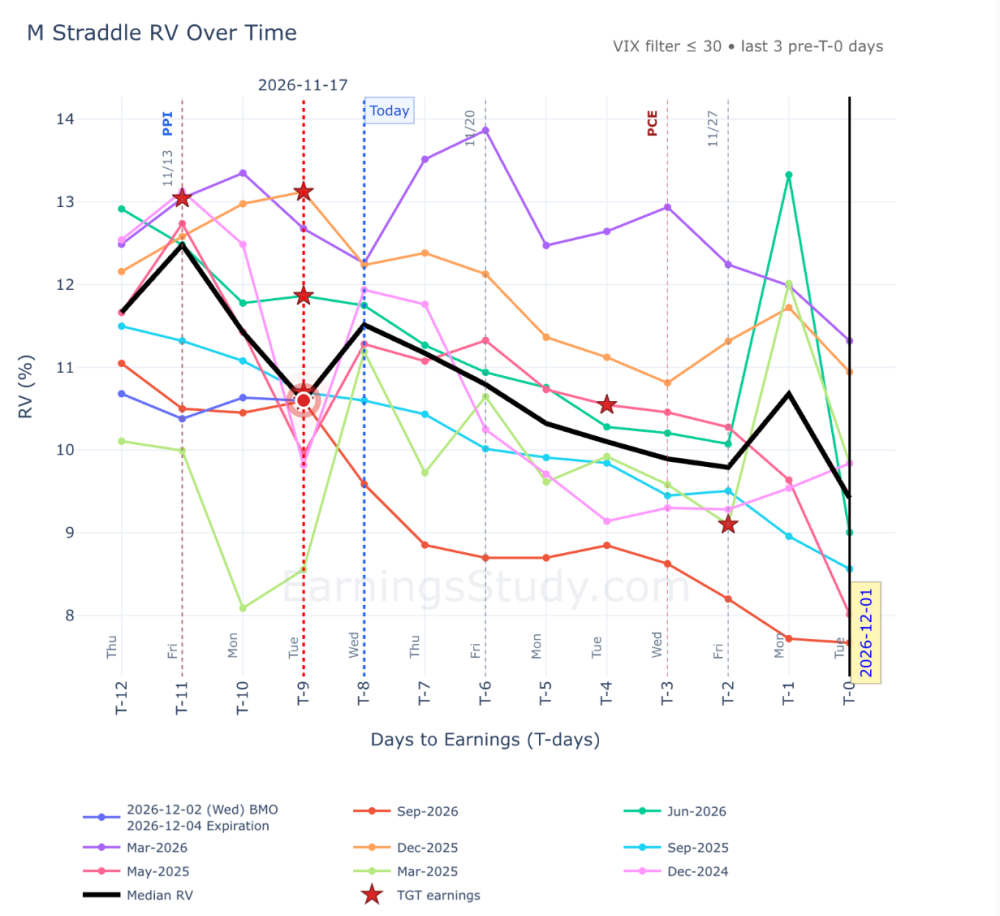
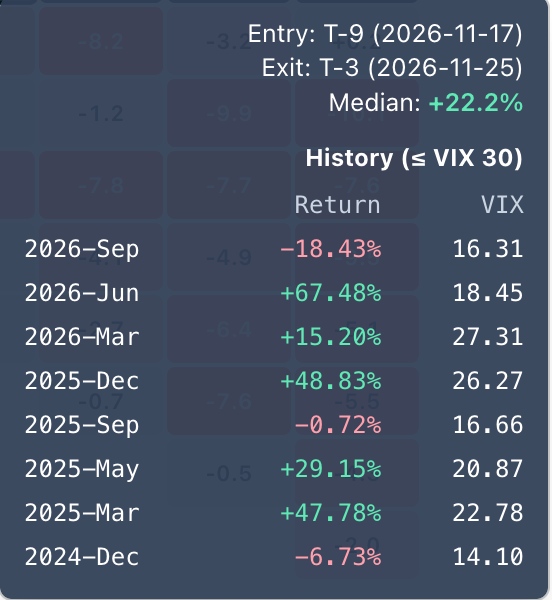
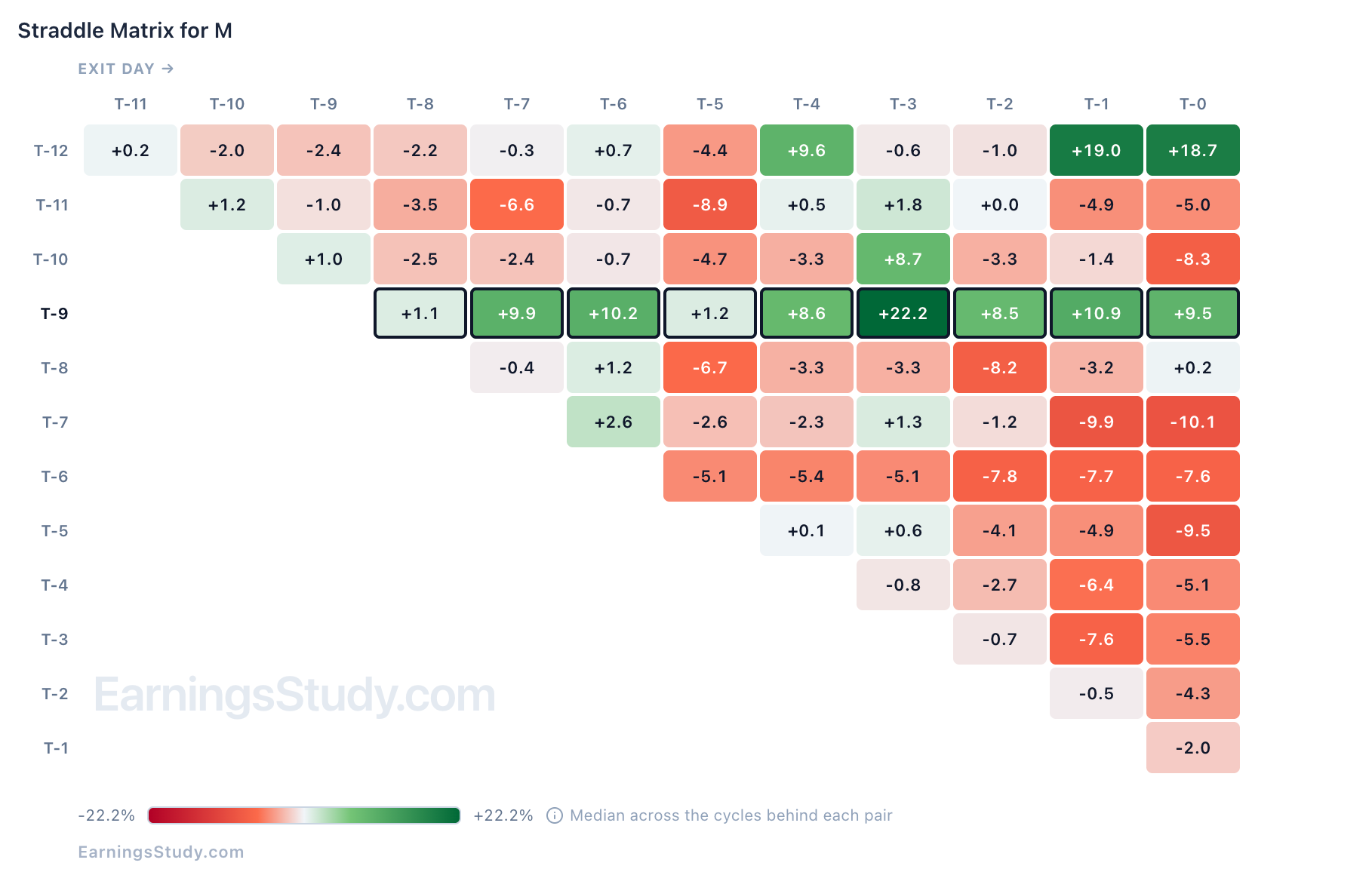
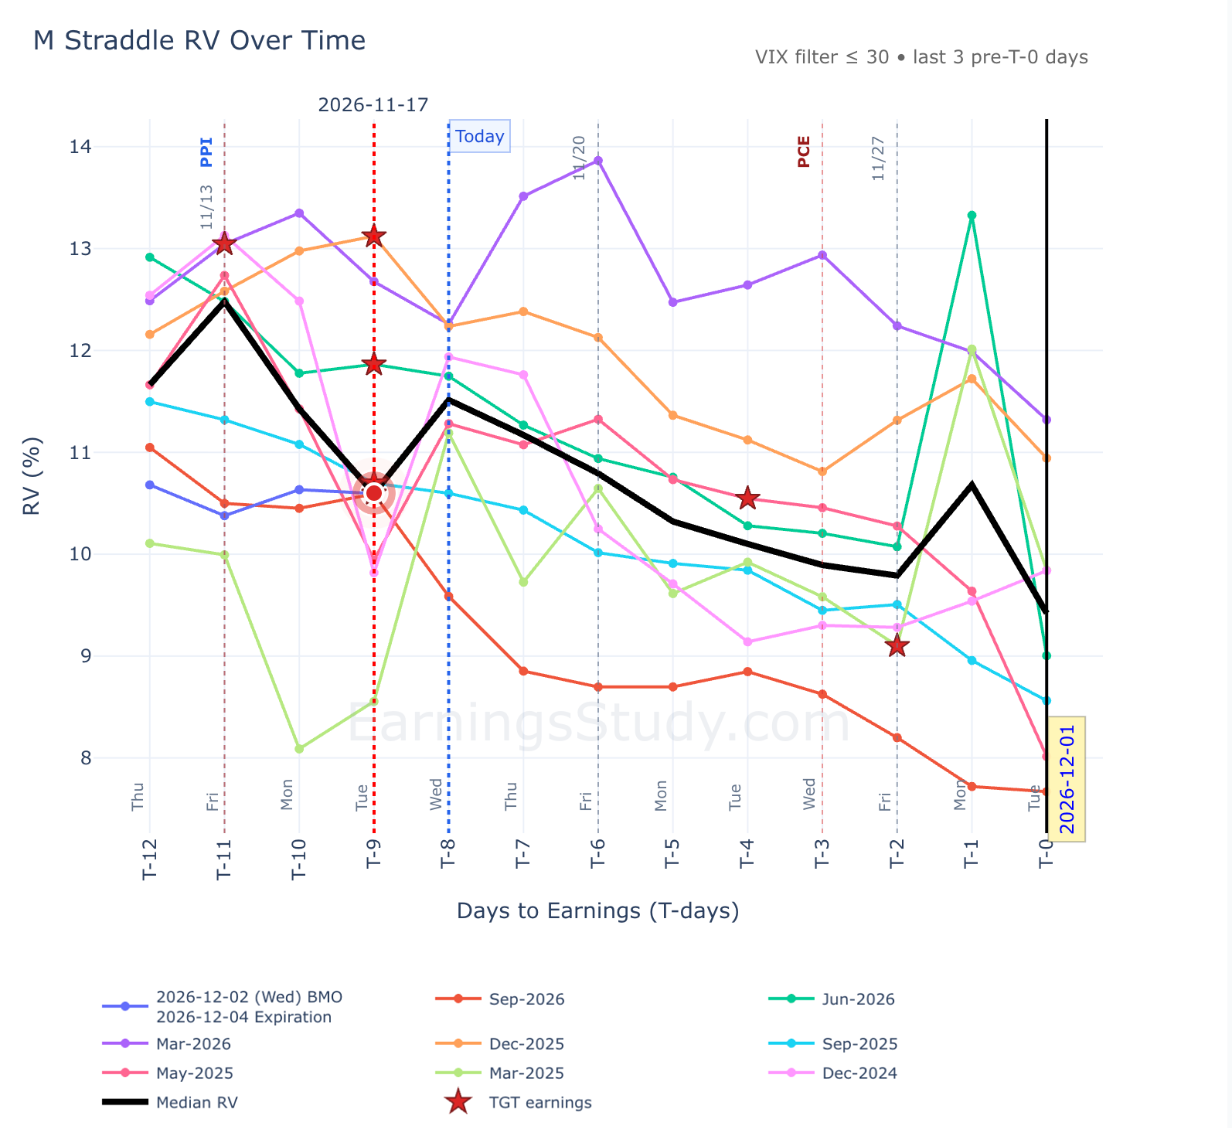
M: one green row, and what TGT had to do with it Yesterday I opened M's Straddle page. M reports Dec 2 before the open, so Dec 1 is the last day to hold. One row of the History Matrix stood out: entering at T-9 was green on every exit, while almost everything around it was red. Across all 78 entry and exit pairs, the typical one returned −2.0%. The T-9 row ran from +1.1% (out the next day) to +22.2% (out at T-3), and +9.5% held to T-0. M Straddle History Matrix, median return, 8 cycles. Yesterday's T-9 row outlined for this post. A row like that usually has a reason. Here's how I went looking for it. 1. The low point on the RV chart. The black median line on the Straddle RV chart dips at T-9: 10.60%, against 11.43% at T-10 and 11.51% at T-8. In past cycles, T-9 was the day M's straddle was cheapest relative to the stock. Yesterday's reading was 10.60%, right on that median. 2. Peer earnings markers. Above the RV chart, Peer earnings marks where a peer's report fell in each of M's past cycles. M's peer list only has KSS, so I chose Custom and typed TGT. The red stars tell the story. In Jun 2026, Dec 2025 and Sep 2025, TGT's last session before its report landed on M's T-9. It did again this cycle: TGT reported this morning, Nov 18, before the open. Entering M at T-9 meant entering the night before a major peer reported. M Straddle RV with TGT earnings marked (stars). EOD data through Nov 17. 3. Check it cycle by cycle. Hover any cell to see the cycles behind it. For T-9 to T-3, the two biggest winners were Jun 2026 (+67.5%) and Dec 2025 (+48.8%), both cycles where TGT reported right after T-9. The third, Sep 2025, was flat (−0.7%). TGT isn't the whole story either: Mar 2025 (+47.8%) and May 2025 (+29.2%) did well without it, and Sep 2026 lost 18.4%. The peer report tipped the odds; it didn't guarantee anything. One more detail: in the TGT cycles the gain mostly didn't arrive overnight. T-9 to T-8 was +4.4%, −7.2% and −2.2%, and the gain built over the following week. Cycles behind T-9 → T-3 (hover any cell). 4. Plan the exit before you enter. Switch the matrix to Reached target and pick +20%. From a T-9 entry, 3 of 8 cycles reached +20% by the very next day, and 5 of 8 had reached it by T-4. That's where a GTC profit order would have filled. This cycle. The Trade Details card showed the Dec 4 $23.50 straddle at $2.49 at yesterday's close. After TGT reported this morning, the same straddle was trading around $2.96, up about 19% in a day. A +20% GTC from $2.49 would sit at $2.99. Now look at today's row. Enter at T-8, after TGT has already reported, and the row turns red again. The best exit is +1.2% at T-6, and only 2 of 8 cycles ever reached +20%. The setup was the day before the peer reported, not the day after. To do this on any name: Look for a row or column that doesn't match its neighbors. Check the RV chart for a dip on that day. Use Peer earnings (or Custom) to see whether a peer's report lines up. Hover the cells to see which cycles carried it. Use Reached target to choose a realistic GTC before you enter. A caution: this rests on 8 cycles, and only 3 of them had TGT at T-9. Treat it as a reason to look, not a rule. Peer dates shift from cycle to cycle, so check where the star sits in the current cycle before relying on it. Educational research only, not trade advice. Based on EOD data; past cycles don't guarantee future results.
 1 point
-
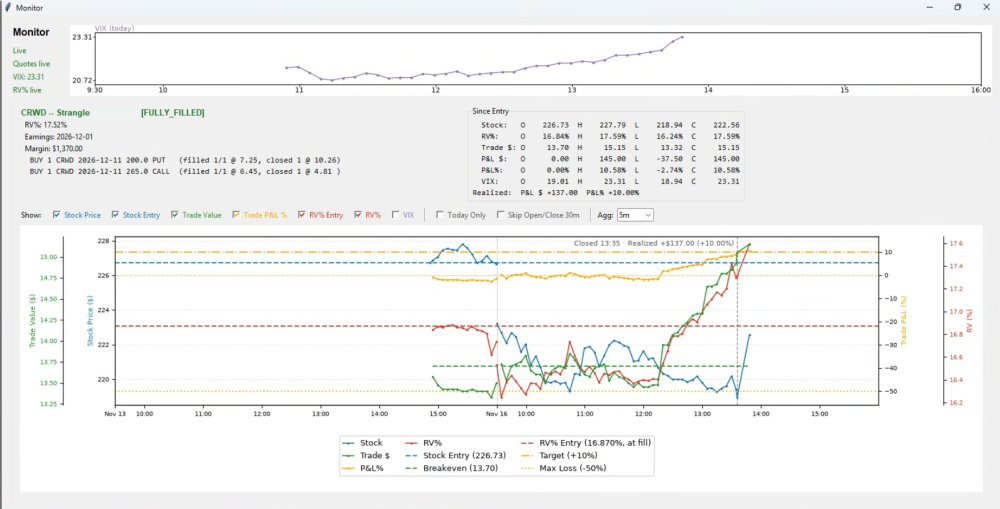
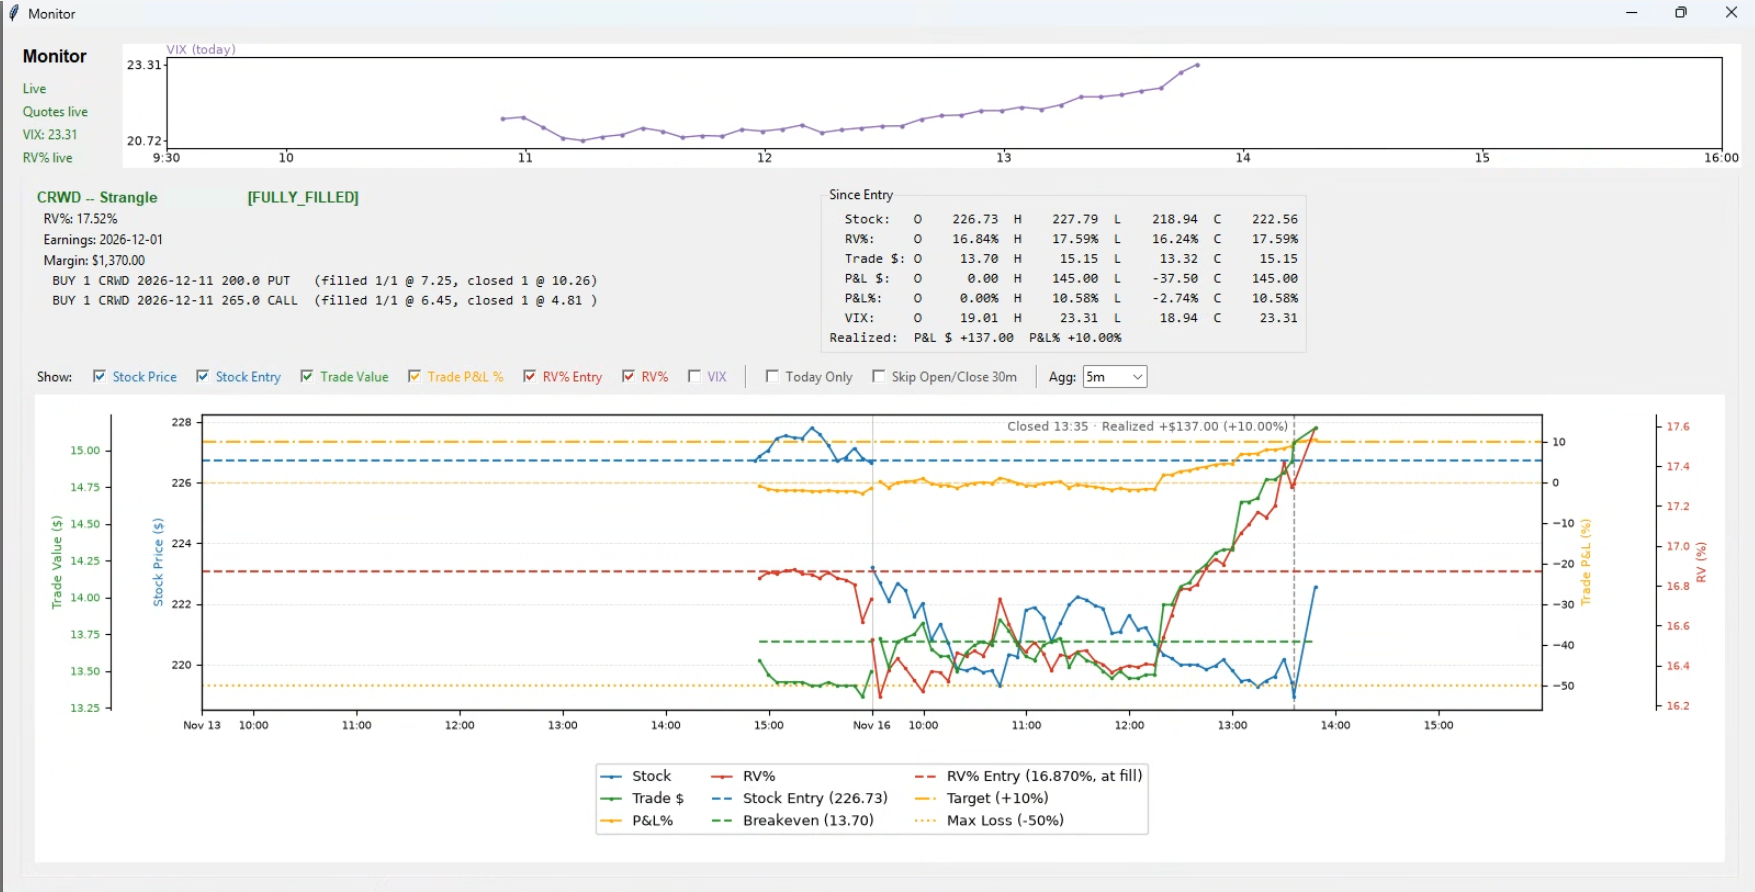
A CRWD pre-earnings strangle, start to finish — what the scanner showed, what a member did with it Posted with Canuck Dave’s permission; the chart is his. What OptionBench showed. On the Pre-Earnings scanner, CRWD (earnings 1 December, confirmed) carried a Long Strangle row entered at T-12. Over the 24 past cycles the card publishes, the position closed up 10% or more at some point in 20 of them (83%). The same card shows two returns side by side, and the gap between them is the point of this post: +18% at the observed exit (where the position stood when it was closed in the backtest) against +3.6% for a resting order at +10%, losers included. High hit rate, modest average for the order that actually gets filled. What Dave did. He entered a day late, at T-11, on Friday 13 November: the card flags a late entry as a different trade, and the T-11 row’s own figures (79%, +0.7% at the target) were visible. The combo was quoted 13.90 / 15.30; OptionBench priced the position at 13.72 (mid + 0.5% a leg, the convention behind every statistic on the site), above the historical median entry of about $11, which the cheapness gauge said. He worked a limit and was filled at 13.70. He also had a stop in mind, on price and on time, before he was in. On Monday 16 November at 13:35 ET his resting order at +10% filled at 15.07: +$137 on one contract, +10.0%, in two sessions. What the chart says. CRWD closed Monday at 222.56 against an entry at 226.73; the stock went down 1.8%. The gain came from the premium itself: RV (position cost ÷ spot) rose from 16.87% at his fill to 17.59% at his exit, with the VIX going from 19 to 23 through the session. That is the pre-earnings long-vol trade in one picture: you are long the run-up in implied volatility into the print, not a direction. And the two conventions, live. After his exit the position kept rising: it traded up to about +17% in the last hour and ended the session above his fill. OptionBench’s observed-exit statistic will book that higher figure; Dave’s account books +10%. Neither is wrong: one is the path, the other is the order. The card shows both so that nobody mistakes the first for the second, and this trade is a clean illustration of why a resting order at the target gives up some of the observed return and, in exchange, never depends on being at the screen. The caveat, as always. One trade proves nothing about the next. The record says the target is reached often and that a resting order at it earns little on average, because the cycles that never get there give back 30–50% of the debit. Dave sized it for that and sat through a −2.7% dip on day one without touching it. The scanner surfaced the row, the card priced it and showed both sides of the record, and a member executed it with his own rules. That division of labour is what the tool is for. Romuald, optionbench
 1 point

This leaderboard is set to New York/GMT-05:00